Ask most small business owners why accounting matters, and you will often get a simple answer: “Because HMRC and Companies House require it, and I do not want a fine.”
Tax returns, statutory accounts, and legal compliance are necessary. But treating accounting as nothing more than a yearly administrative task can be an expensive mistake. The real value of accounting is in financial control, better decisions, and early risk detection.
Without accurate financial records, it is difficult to know whether the business is actually profitable, which clients are costing you money, when you can afford to hire, or why the bank balance is falling even when sales are increasing.
Here are six practical reasons why accounting matters to business owners, along with what can happen when the numbers are ignored.
6 reasons why accounting matters to every business owner
| Area | What accounting helps with |
|---|---|
| 1. Cash flow visibility | Knowing when money will come in and when it needs to go out |
| 2. Decision-making | Making hiring, investment, and pricing decisions using real figures |
| 3. Profitability | Understanding the difference between revenue, margins, profit, and cash |
| 4. Tax planning | Planning ahead for tax and using available reliefs correctly |
| 5. Funding and credibility | Giving banks, investors, and landlords reliable financial information |
| 6. Fraud prevention | Finding errors, unusual payments, and weaknesses in financial controls |
1. Cash flow predictability: why profitable businesses can still fail
One of the most common misunderstandings in business is that profit automatically means financial security. It does not.
A business could report £100,000 in net profit on its profit and loss statement while having only £200 in the bank. If payroll is due on Friday, that business still has a problem.
This can happen because of the working capital gap. For example:
- You complete a service or ship goods in January.
- You send the client an invoice on 30-day terms, but the client takes 60 days to pay.
- Your employees, rent, software licences, and VAT still have to be paid on time.
The profit may exist on paper, but the cash has not arrived yet.
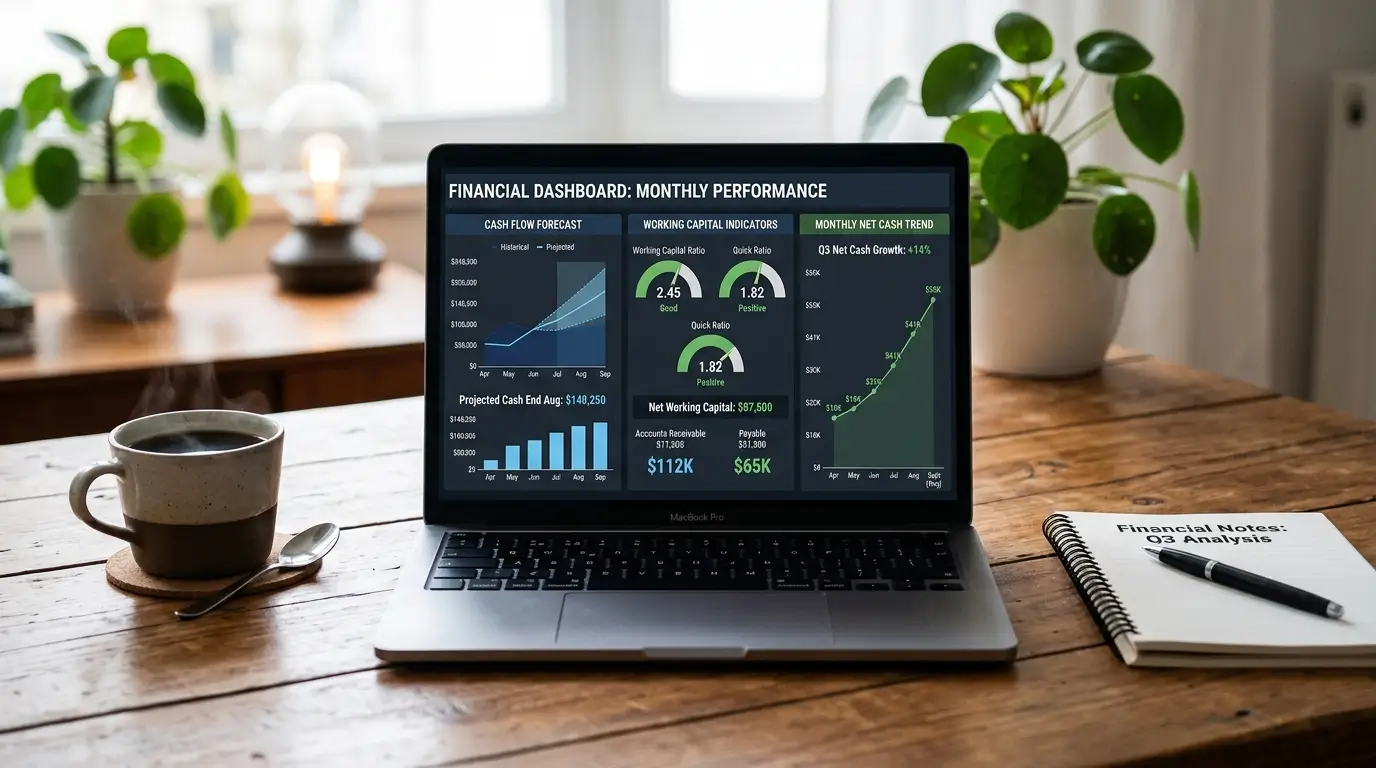
How accounting helps: A 13-week rolling cash flow forecast gives you a clearer view of expected receipts and payments. It can track Accounts Receivable, which is money owed to you, and Accounts Payable, which is money you owe to others.
This can help you spot a potential cash shortage several weeks in advance. You then have time to chase overdue invoices, change payment terms, or arrange short-term finance before the problem becomes urgent.
2. Better decision-making: removing the guesswork
Growth usually requires spending money. Without reliable financial information, owners can end up making important decisions based on the current bank balance, instinct, or sales figures alone.
| Business question | Weak approach | Better approach |
|---|---|---|
| Can we hire a senior manager at £65k? | Look at the bank balance and assume the business can afford it. | Calculate the full employment cost, including Employer NICs, pension, and tools, then work out how much extra revenue is needed to protect the net margin. |
| Should we reduce our core service price by 15%? | Assume higher sales volume will make up for the lower price. | Run a contribution margin analysis and calculate the additional sales volume required to break even. |
| Can we open a second location? | Base the decision mainly on confidence and expected demand. | Model the extra fixed costs and test them against seasonal changes in revenue using historical management accounts. |
The point is simple: good accounting gives you numbers to work with before you commit the business to a major cost.
3. Understanding true profitability
Revenue can look impressive, but revenue alone does not tell you whether the business is healthy.
Imagine a company with £2 million in annual turnover and a 2% net profit margin. That leaves just £40,000 in net profit. A delayed client payment or unexpected cost could put serious pressure on the business.
Now compare that with a boutique agency generating £500,000 in turnover with a 30% net margin. That produces £150,000 in net profit.
Accounting helps you break the figures down into different levels of profitability.
- Gross margin: Revenue minus the cost of goods sold. This helps you see whether your pricing and direct delivery costs make sense.
- Operating margin: Gross profit minus operating overheads. This shows how efficiently the business is managing its operating and administrative costs.
- Net profit: The profit left after expenses, interest, and taxes. This is the bottom-line return generated for shareholders.
Looking at these figures separately gives you a much better picture than looking at turnover alone.
4. Proactive tax planning: keeping more of what you earn
Waiting until the end of the financial year to look at your tax position leaves very little room for planning. Once the year has closed, many decisions have already been made.
Good accounting keeps your tax position under review during the financial year. Depending on the business and its circumstances, this can include:
- Planning how profits are extracted: Looking at salary, dividends, director loan accounts, and pension contributions.
- Using available tax reliefs: Considering areas such as Full Expensing, Annual Investment Allowance (AIA), and R&D Tax Relief where applicable.
- Reviewing VAT arrangements: Considering whether the Standard VAT scheme, Flat Rate Scheme, or Cash Accounting scheme is appropriate for the business.
The aim is to stay within HMRC rules while making proper use of the tax reliefs and allowances available to the business.
5. Securing bank finance, investment, and commercial leases
When you apply for business finance, seek investment, or take on a commercial lease, the other party will want to understand the financial position of your company.
Financial statements and current management accounts can provide that evidence. If your records contain unreconciled spreadsheets, missing information, or overdue filings, the process becomes much harder.
- Lenders may reject an application or offer finance on less favourable terms.
- Investors may reduce their valuation of the business during due diligence.
- Commercial landlords may ask for larger deposits or other forms of security.
Clean and well-maintained accounts make it easier for other parties to assess the business and its financial history.
6. Preventing fraud, errors, and financial leakage
Small and medium-sized businesses can be exposed to financial losses when there are weak controls or too much responsibility placed with one person.
Common problems include:
- Duplicate supplier payments
- Unused recurring software subscriptions
- Unauthorised staff credit card expenses
- Fraud involving changes to supplier bank details
How accounting helps: Regular bank reconciliations, three-way matching, and separation of financial duties make it harder for errors and unauthorised payments to go unnoticed.
Three-way matching compares the purchase order, delivery note, and supplier invoice. When these records agree, the payment has a clear paper trail behind it.
What happens when a business owner ignores accounting?
Poor accounting can create a chain of problems. Incomplete bookkeeping means the owner has less visibility over margins and cash flow. That can lead to poor pricing, uncontrolled spending, or hiring decisions that the business cannot comfortably support.
The problems can then reach tax payments and working capital. By the time the owner sees the full picture, there may be little time left to fix it.
| Problem | Possible result |
|---|---|
| Incomplete bookkeeping | Unclear financial position |
| Poor visibility of margins and cash flow | Weak pricing and spending decisions |
| Uncontrolled spending or hiring | Pressure on working capital |
| Unexpected tax liabilities | Cash flow problems and penalties |
| Constant financial firefighting | Less time and money available for running the business |
Frequently asked questions
Can I run a successful business without understanding accounting?
You do not need to become a qualified accountant. But you should understand the basic financial numbers that affect your business.
At a minimum, a business owner should understand gross margin, cash runway, debtor days, and the difference between profit and cash flow.
It is sensible to delegate bookkeeping and technical accounting work to professionals. Handing over all responsibility for understanding the financial position of the business is a different matter.
How often should a business owner review accounting reports?
The right frequency depends on the size and complexity of the business, but a useful routine can look like this:
- Weekly: Review the bank balance, expected customer receipts, and immediate supplier payments.
- Monthly: Review management accounts, including the profit and loss against budget, balance sheet reconciliations, and aged debtors and creditors.
- Quarterly: Review VAT returns, Corporation Tax accruals, and rolling 12-month forecasts.
What is the ROI of investing in professional accounting?
Professional accounting can generate a return in several ways. It can help a business:
- Find and claim tax allowances that might otherwise be missed.
- Avoid late filing penalties and unnecessary interest charges.
- Reduce the risk of expensive hiring and expansion decisions based on incomplete figures.
- Give the owner more time to focus on sales, customers, and the wider business.
Treat accounting as a business asset
Accounting is about more than keeping HMRC satisfied. It gives a business owner a clearer view of what is happening with cash, costs, tax, and profit.
When the numbers are accurate and reviewed regularly, you can make decisions with a much better understanding of what the business can afford. That matters when you are hiring, changing prices, investing, taking on finance, or considering expansion.
M&M Finance Advisory helps founders and business directors with accounting, tax planning, management reporting, and Virtual CFO support. If you want to use your financial information to make better commercial decisions, speak to the advisory team about your business.